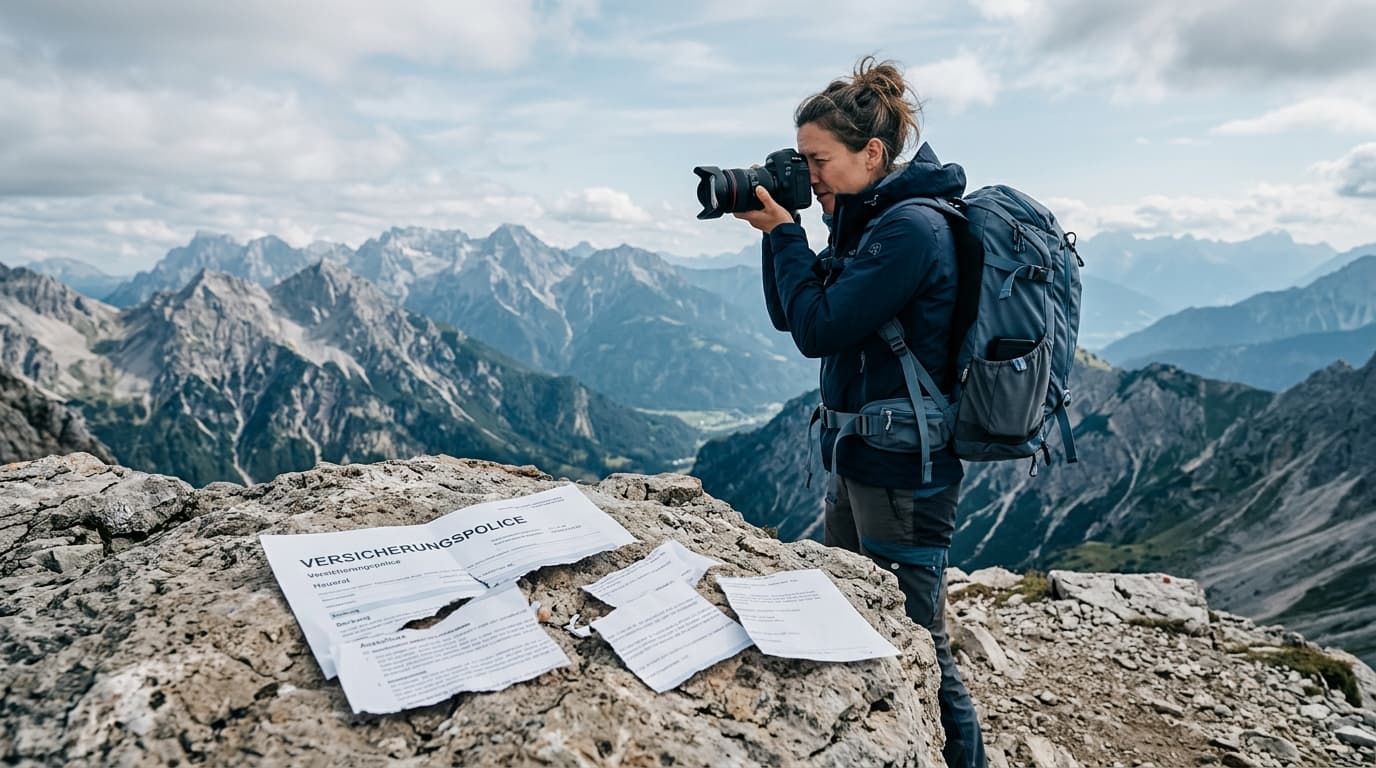
Camera Insurance: What Home Contents Insurance Doesn't Cover
Camera insurance explained: what damage home contents insurance doesn't cover, what happens on the go and in commercial use, and why a separate policy
All details are taken from the provider's linked product page and the contract documents (IPID/policy conditions) published there; the insurer's documents prevail. Premiums, benefits and the insurance product itself may change – please verify the details directly with the partner before signing up; only the information provided there is binding.
 Katrin StraubManaging DirectorInsurance expert with over 20 years of experience in the insurance industry.
Published on
11 min read
Table of Contents
Yes, at home your camera is covered by home contents insurance against burglary, robbery and fire. No, not on the go: simple theft, drop and breakage damage, and commercial use are typical gaps that a dedicated camera insurance closes.
Camera Equipment Insurance
Secure your valuable camera equipment thoroughly against damage, theft, and loss with the camera equipment insurance from nextsure. Tailored protection for professionals and hobby photographers.
Learn moreWhat home contents insurance really covers for your camera
Yes, at home the camera is usually covered by home contents insurance, but only against certain perils and only within the home. Burglary is present when the perpetrator overcomes an obstacle and enters a locked room, for example a forced door lock or a smashed window. Home contents insurance replaces household property destroyed or damaged by fire, lightning strike, explosion, burglary, storm from wind force 8, hail, tap water or power surge.[1] Anyone who leaves windows and doors open or tilted, however, risks the insurer reducing the payout due to gross negligence.[1]
The crucial catch: the protection applies to the home, not to photography. The camera counts as ordinary household property, not as valuables: valuables with their own compensation limits include cash, jewellery, furs, hand-knotted carpets and antiques, while computers and other electronic devices fall under ordinary household property.[1] That sounds good at first, because it means no additional compensation limit. But it does not change the covered perils — and that is exactly where the gap lies.
- Covered at home: burglary, fire, lightning strike, storm, hail, tap water and power surges.[1]
- Not covered: simple theft, i.e. taking something without breaking in and without force.[2] Only items taken from a locked room or a secured container are replaced.
- Not covered, even at home: drop and breakage damage as well as damage caused by operating errors and improper handling. They do not appear in the perils catalogue of home contents insurance at all.[1]
So if you only drop the camera off the table at home or knock the lens against the door, you are left with the costs despite home contents insurance. And anyone who takes photos usually does not do so at home. Precisely where the camera is actually in use, home contents insurance coverage typically ends.
On the go and on holiday: the four typical coverage gaps
Away from home, home contents insurance only applies to a limited extent. So-called external insurance applies when home contents are temporarily outside the home, worldwide, but always for a limited period: the deadline varies by provider and ranges from a few weeks to six months.[2] It also only pays for the same perils as at home, for example burglary from your hotel room or a broken-open locker, but not for simple theft.[2] Robbery only applies when someone uses force or credibly threatens to use force.[3] These four gaps regularly remain uncovered:
- Simple theft on the go: If someone takes the camera from the chair while you are sitting in the ice cream parlour, that is simple theft and therefore not insured.[2]
- Theft from a vehicle or tent: According to the German Insurance Association (Gesamtverband der Deutschen Versicherungswirtschaft) and case law, a motor home is not considered a separate room, so external insurance generally does not apply to theft from caravans, motor homes, awnings or tents.[2]
- Drops, breakage, sand and liquids: These damages appear in no perils catalogue of home contents insurance, whether at the beach, at a festival or at home.[1]
- Time limit: External insurance coverage is limited in time, depending on the provider to a few weeks up to six months. For longer stays or storage, it expires while your equipment is still out of the house.[2]
One example makes it concrete: You place the camera next to you on the bench, and while you briefly pop to the kiosk, it disappears. Because no obstacle was overcome and no force was used, this does not count as burglary or robbery, but as simple theft — and that is generally not insured under home contents insurance.[3] Yet situations like these — markets, festivals, street photography — are the normal case of photography outside your own four walls.
Commercial use: when private policies end
The clear rule is: private policies and home contents insurance are geared towards private household belongings. For commissioned work and commercial use, they do not apply. This is the most common misconception on this topic. If you earn money with your camera, you need your own solution, because a private policy does not cover commercial risks as a matter of principle.
The distinction that decides the case lies in paid use. Occasional photos for your own blog are one thing; paid commissioned work is another. As soon as a fee flows, a client accepts the results or the photos serve advertising purposes, the use is paid and therefore commercial. Even at home, private protection ends at this boundary: a home office recognised for tax purposes generally no longer falls under the home contents policy and requires separate cover.[1] For commercial use, dedicated electronics or photography insurance for business customers is intended, covering equipment, studio inventory and assignments abroad.
Whether your case falls under this cannot be answered in general terms. It depends on how often you take paid photos, to what extent and with what equipment. This is exactly where an assessment through independent advice pays off — before a claim is denied because the use was not private.
What camera insurance covers instead (market status 2026)
A dedicated camera insurance policy closes exactly the gaps that home contents insurance leaves open. Typical scope of cover on the market in 2026: worldwide protection against drop, breakage, sand and liquid damage, short circuit and vandalism, while theft usually comes as an optional module.[4] Unlike home contents insurance, such a tariff does not work with a short list of perils, but explicitly lists which types of damage are excluded.
The camera insurance brokered via nextsure (the risk carrier is Hiscox SA, Niederlassung für Deutschland) covers cameras and camera equipment including original accessories worldwide.[4] Both new and used devices are insured, provided they are clearly identified in the insurance certificate by their serial number.
- Included in the basic cover: drop, breakage, sand and liquid damage, mechanical impact, fire, overvoltage, short circuit, vandalism as well as operating errors and improper handling.[4]
- Optional as a theft module: theft while being carried securely within sight or body contact, burglary theft from a locked car or locked room, as well as robbery and looting.[4]
- Not insured: loss through leaving behind, forgetting or losing the device, damage covered by the manufacturer's warranty, grossly negligent or intentional acts.[4]
- Reporting obligations: report a claim online within 14 days; in case of theft, robbery or vandalism, report to the police within 24 hours.[4]
The premium is based on the replacement value of the equipment, the chosen deductible — that is, the share you bear yourself in the event of a claim — and the sum insured. The amount of the sum insured is not quantified in the product data sheet; it results from the insurance certificate.[4] Whether a tariff is accepted in an individual case and what the specific cover looks like is always decided by the insurer based on its acceptance decision and the contract documents. A general article cannot promise cover or acceptance.
Documenting your equipment: serial numbers, values, a worked example
Regardless of whether you take out your own policy, clean documentation pays off. In the insurance certificate, each device is identified by its serial number or its IMEI, the globally unique identifier of mobile devices. Without this number, a device cannot be insured.[4] Keep your purchase receipts and photograph your equipment — in the event of a claim, this makes it easier to prove what you had and what it was worth.[1]
The basis for the sum insured and the premium is the replacement value of the entire equipment, i.e. camera body, lenses and original accessories added together. The higher this replacement value and the lower the deductible, the higher the premium. To do this, go through your equipment position by position:
| Item | Note |
|---|---|
| Camera body | record the replacement value, note the serial number |
| Lenses | record each lens individually with its replacement value and serial number |
| Accessories | [4]only original accessories are covered, not items bought separately or later |
| Total replacement value | sum of the items, the basis for the sum insured and the premium |
Higher sums insured and lower deductibles increase the premium. Which tariff ultimately fits depends on these criteria. A general article cannot decide this or designate any tariff as the best.
Conclusion: well protected at home, usually not on the go
The general rule in one sentence: home contents insurance covers your camera at home against burglary, robbery and fire, but not the risks of photography itself. Simple theft while out and about, drop and breakage damage, and commercial use remain uncovered. If you only photograph at home, you usually need nothing extra. If you work on the go or take on assignments, you need your own solution.
Which cover suits you depends on how you use your equipment, its value and the risks you want to bear yourself. Tariffs and conditions change constantly, so it is worth taking a look at the current market before every policy purchase.
If you would like to know whether a dedicated tariff makes sense for your usage, you can book a consultation and go through your equipment position by position together.
Frequently asked questions
- Is my camera covered by home contents insurance?
Yes, but with limitations: at home, the camera is insured as part of your household contents against burglary, robbery, vandalism, fire and water damage from burst pipes. Drop, breakage and accidental damage are not covered at home either, and away from home the protection only applies within narrow limits via extended coverage outside the home.
- What is the difference between burglary and simple theft?
Burglary occurs when the perpetrator breaks into a locked space, for example forcing open an apartment or a hotel room. Simple theft is taking something without breaking in and without force, for example when someone snatches the camera at a market stall. Home contents insurance only covers burglary, not simple theft.
- Is my camera insured while on holiday?
In principle yes, via the so-called extended coverage of home contents insurance, usually worldwide and for temporary stays. However, the time limit is restricted and ranges depending on the provider from a few weeks up to six months. Only break-in to a building, such as a hotel room, and robbery are covered. If the camera is taken on the open street, this counts as simple theft and is not insured.
- Does home contents insurance pay out if the camera falls?
No. Drop, breakage and accidental damage are not covered by home contents insurance, not even at home. These are precisely the damages that form the core of a dedicated camera insurance, which covers drops, breakage, sand and liquid damage worldwide.
- What happens if I earn money with my camera?
With commercial use, i.e. paid assignments, private tariffs and home contents insurance generally do not apply; photo equipment is then considered business assets. Separate electronics or photo insurances for commercial customers are provided for this. If you only photograph privately, a private tariff is sufficient.
- How much does camera insurance cost?
The premium depends on the replacement value of the equipment, the deductible and the sum insured. Cheap tariffs for individual devices start in the low single-digit euro range per month, while high-quality equipment costs correspondingly more. The exact price depends on the individual tariff.
- Is the camera also replaced if it is stolen from a car?
Via home contents insurance only if the car was parked in an enclosed building such as a multi-storey or underground car park, not at street parking spots. In a camera insurance, burglary from a locked vehicle, for example from a non-visible boot, is typically part of the optional theft module.
Sources
Conclude directly online
Verified partner tariffs at no extra cost. The button takes you straight to the provider's calculator.
 Hepster
Camera insurance
Worldwide cover for new and used cameras, including original accessories.
- Coverage area:
- worldwide
- Battery-wear threshold:
- up to 60% remaining capacity, device max. 4 years old
- Minimum term:
- 3 months (monthly subscription)
- Drop, breakage, sand, and liquid damage
- Fire, explosion, power surge, short circuit, sabotage, vandalism
- Battery and screen damage, plus battery wear (where not covered by warranty)
- Operating errors and improper handling
- Theft module: theft, burglary from a car or home, robbery
Key exclusions
- Loss and forgetting outside the insured theft scenarios
- Devices without a known serial/IMEI number
- Damage covered under warranty or manufacturer's guarantee
- Gross negligence or intentional acts
Trusted Shops: 4,5/5 „Sehr gut“ (2.600 Bewertungen)
hepster insgesamt (Anbieterbewertung, alle Versicherungen)
Claims must be reported online within 14 days; theft must be reported to the police within 24 hours. Insurer: Hiscox SA, Niederlassung für Deutschland
Fact sheet: benefits, exclusions and waiting periods in detail
All details are taken from the provider's linked product page and the contract documents (IPID/policy conditions) published there; the insurer's documents prevail. Premiums, benefits and the insurance product itself may change – please verify the details directly with the partner before signing up; only the information provided there is binding.
Information last updated: July 2026 · Source: provider product information (IPID/policy conditions)